These people can get their money back! The final settlement of individual tax comprehensive income is about to start.
CCTV News:According to the website of State Taxation Administration of The People’s Republic of China, in order to effectively safeguard the legitimate rights and interests of taxpayers, and establish and improve the system for the final settlement and payment of individual income tax comprehensive income in a reasonable and orderly manner, according to the relevant provisions of the Individual Income Tax Law and its implementing regulations (hereinafter referred to as the "tax law") and the tax collection and management law and its implementing rules, the relevant matters concerning the final settlement and payment of individual income tax comprehensive income in 2020 (hereinafter referred to as the "annual settlement") are hereby announced as follows:
I. Contents of annual settlement
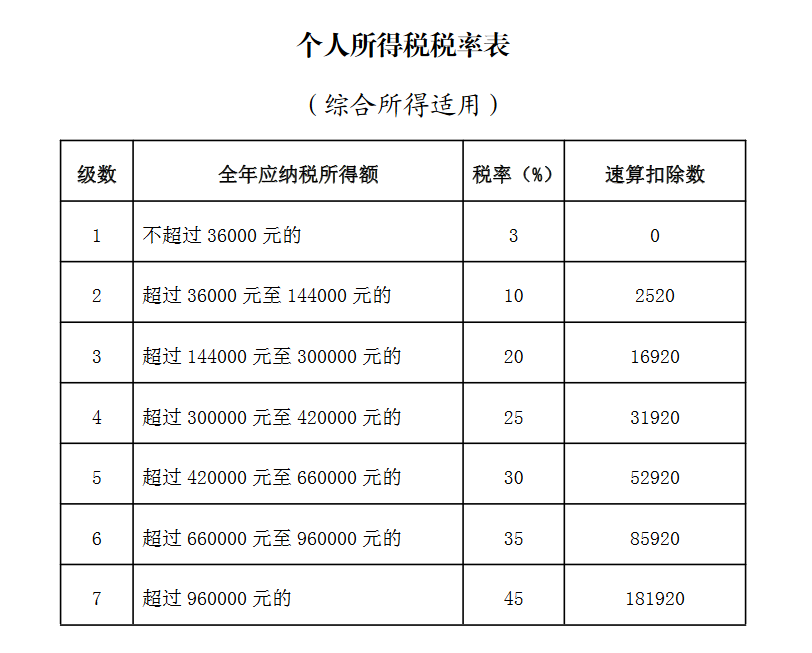
According to the provisions of the tax law, after the end of the year 2020, individual residents (hereinafter referred to as "taxpayers") need to summarize the income of four incomes (hereinafter referred to as "comprehensive income") obtained from January 1 to December 31, 2020, and deduct expenses of 60,000 yuan, special deductions, other deductions determined according to law and eligible charitable donations. Apply the personal income tax rate of comprehensive income and subtract the quick deduction, calculate the final tax payable this year, and then subtract the prepaid tax in 2020 to get the tax amount to be refunded or supplemented, and report to the tax authorities and apply for tax refund or supplementary tax. The specific calculation formula is as follows:
Refundable or payable tax = [(comprehensive income-60,000 yuan-special deductions such as "three insurances and one gold"-special additional deductions such as children’s education-other deductions determined according to law-donation) × applicable tax rate-quick deduction]-prepaid tax in 2020
According to the provisions of the tax law, the annual settlement does not involve classified income such as property leasing, and income such as annual one-time bonus that taxpayers choose not to be incorporated into comprehensive income for tax calculation according to regulations.
Two, taxpayers who do not need to apply for annual settlement.
Approved by the State Council, according to the Ministry of Finance   Announcement of the State Administration of Taxation on Relevant Policy Issues Concerning the Settlement and Payment of Comprehensive Income of Individual Income Tax (No.94, 2019) stipulates that if a taxpayer has paid personal income tax in advance in 2020 according to law and meets any of the following circumstances, it is not necessary to apply for annual settlement:
(a) the annual final settlement needs to pay taxes, but the comprehensive income does not exceed 120 thousand yuan;
(two) the annual amount of tax payment does not exceed 400 yuan;
(3) The amount of tax paid in advance is consistent with the annual tax payable or no tax refund is applied.
3. Taxpayers who need to handle annual settlement.
According to the provisions of the tax law, taxpayers need to apply for annual settlement under any of the following circumstances:
(a) the prepaid tax amount is greater than the annual tax payable and applies for tax refund;
(two) the comprehensive income of more than 120 thousand yuan for the whole year and the amount of tax payment is more than that of 400 yuan.
Four, can enjoy the pre-tax deduction.
For the following pre-tax deduction items that occurred in 2020 and were not declared or fully deducted, taxpayers can apply for deduction or supplementary deduction during the annual settlement period:
(a) the taxpayer and his spouse, minor children meet the conditions of serious illness medical expenses;
(2) Taxpayers’ eligible special additional deductions for children’s education, continuing education, housing loan interest or housing rent, and support for the elderly, as well as deductions for expenses, special deductions and other deductions determined according to law;
(3) Taxpayers’ eligible donation expenses.
V. Processing time
The annual settlement time is from March 1 to June 30, 2021. Taxpayers who have no domicile in China leave the country before March 1, 2021, and can make annual settlement before leaving the country.
VI. Handling Methods
Taxpayers can choose the following handling methods:
(a) to handle the annual settlement;
(2) Personal income tax obtained by employing units (including units that withhold and prepay their labor remuneration according to the cumulative withholding method, the same below). Hereinafter referred to as the "unit") for.
If a taxpayer asks for the agency, the unit shall handle it on his behalf, or train and guide the taxpayer to complete the annual final declaration and tax refund (compensation) through the online tax bureau (including mobile personal income tax APP, the same below).
If it is handled by the unit on its behalf, the taxpayer shall confirm with the unit in writing or electronically before April 30, 2021, and provide supplementary information such as comprehensive income, relevant deductions and tax preferences obtained outside the unit in 2020, and be responsible for the authenticity, accuracy and completeness of the information submitted. If the taxpayer has not confirmed with the unit to ask it to handle the annual settlement on its behalf, the unit may not do it on its behalf.
(3) Entrusting tax-related professional service institutions or other units and individuals (hereinafter referred to as "the trustee"), and the trustee shall sign a power of attorney with the taxpayer.
After the unit or trustee handles the annual settlement for the taxpayer, it shall promptly inform the taxpayer of the handling situation. Taxpayers who find that there are errors in the declaration information may request the unit or the trustee to make corrections, or they may make corrections themselves.
VII. Handling channels
In order to facilitate taxpayers, tax authorities provide taxpayers with efficient and fast online tax channels. Taxpayers can give priority to the annual settlement through the online tax bureau, and the tax authorities will provide taxpayers with the pre-filling service of the declaration form according to regulations; If it is not convenient to handle it through the above methods, it can also be handled by mail or at the tax service hall.
If you choose to declare by mail, the taxpayer shall send the declaration form to the address announced by the tax bureau of the province, autonomous region, municipality directly under the Central Government and cities with separate plans where the competent tax authorities are located as determined in Article 9 of this announcement.
Eight, reporting information and data retention
Taxpayers who apply for the final settlement in 2020 shall apply to the annual self-declaration form of individual income tax. If it is necessary to modify their basic information and enjoy new deductions or tax concessions, they shall also fill in relevant information as required. Taxpayers need to check carefully to ensure that the information filled in is true, accurate and complete.
Taxpayers and agencies handling annual settlement shall keep their annual settlement returns and relevant information such as taxpayers’ comprehensive income, deduction, tax paid or tax preference for 5 years from the end of the annual settlement period.
Nine, the tax authorities to accept the annual final declaration.
In accordance with the principle of convenience and proximity, if the taxpayer handles the annual settlement on his own or on behalf of the taxpayer, he shall report to the competent tax authorities of the employer where the taxpayer works; If there are two or more employed units, they can choose to declare to one of them.
If a taxpayer does not work for an employer, he shall report to the competent tax authorities at his domicile, habitual residence or main source of income. The main source of income refers to the location of the withholding agent with the largest cumulative income from labor remuneration, manuscript remuneration and royalties obtained by taxpayers in the tax year.
If the unit handles the annual settlement for taxpayers, it shall report to the competent tax authorities of the unit.
Ten, the annual tax rebate, overdue tax
(a) for tax refund
A taxpayer applying for annual tax refund shall provide a qualified bank account opened in China. The tax authorities shall, after auditing according to the provisions, and in accordance with the relevant provisions on treasury management, handle the tax refund on the spot at the location of the tax authorities that accept the annual settlement declaration as determined in Article 9 of this announcement (that is, the settlement place). If the taxpayer fails to provide his valid bank account, or the information provided is incorrect, the tax authorities will notify the taxpayer to correct it, and the taxpayer will apply for tax refund according to law after correcting it as required.
In order to facilitate taxpayers to obtain tax refund, the tax authorities provide convenient tax refund function in the online tax bureau if the comprehensive annual income does not exceed 60 thousand yuan and personal income tax has been paid in advance. Taxpayers can handle the annual tax refund through the simple declaration form from March 1 to May 31, 2021.
Taxpayers who apply for tax refund in 2020 shall apply for tax refund in accordance with the law after applying for tax refund in 2019, correcting the declaration or explaining the relevant situation after being notified by the tax authorities that there are doubts in the declaration in 2019.
(two) for tax payment.
Taxpayers who pay the annual final tax payment can pay through online banking, POS card swiping in the tax service hall, bank counters, non-bank payment institutions, etc. If the declaration is made by mail and the tax is paid back, the taxpayer shall pay attention to the progress of the declaration and pay the tax in time through the online tax bureau or the tax service hall of the competent tax authority.
If the taxpayer fails to fill in the declaration information correctly, resulting in overpayment or underpayment of tax, and the taxpayer takes the initiative or makes timely corrections after being reminded by the tax authorities, the tax authorities may be exempted from punishment in accordance with the principle of "first violation without punishment".
XI. Annual Settlement Service
The tax authorities have launched a series of measures to optimize services, strengthened the policy interpretation and operation guidance of annual settlement, compiled tax guidelines by classification, popularly explained the policy caliber, professional terms and operation procedures, provided prompt and reminder services through multiple channels and forms, and provided tax-related consultation through mobile personal income tax APP, webpage, 12366 tax service platform and other channels to help taxpayers solve difficult problems in handling annual settlement and actively respond to taxpayers’ demands.
In order to reasonably and orderly guide taxpayers to handle the annual settlement, the competent tax authorities will notify taxpayers in batches to remind them to handle it within a certain time period. Taxpayers can make an appointment with the tax authorities or go through the online tax bureau during the annual settlement period if they need to handle it in advance or later. For special groups such as the elderly and the disabled who have difficulties in completing the annual settlement independently, taxpayers apply and the tax authorities can provide personalized annual settlement services.