Digital finance under the blessing of "ecological market" is promoting the upgrading of credit card business of banking giants.
Wen | rang the bell
Source | Technology Direction Theory (xiangling0815)
Stimulating domestic demand has become one of the main tones of current economic development, and reasonable credit consumption is an important way to achieve it, and credit cards from the banking system are undoubtedly the "regular army".
Whether it is the need of macroeconomic development or the awakening of consumers’ personal consumption consciousness, various factors have led to unprecedented pressure on the information system behind bank credit cards-both the substantial increase in business volume and the deepening demand under diversified consumption experiences. It is not enough to upgrade the previous system of banks only, and it must be fundamentally reformed to deal with it.
In this regard, those banks that have been deeply involved in information systems are ahead, and CITIC Bank (601998, Share Bar) credit card is a typical representative.
After successfully passing the test of major nodes such as "Double Eleven", the vitality and technical ability of the new StarCard core system put into operation by CITIC Bank Credit Card in October 2019 one year ago have been confirmed again. On November 24th this year, the first anniversary salon of StarCard’s new core system was held in Shenzhen. With the participation of industrial chain partners, we took stock of and witnessed the growth and achievements of the first new-generation cloud-based credit card core system with independent intellectual property rights in China.
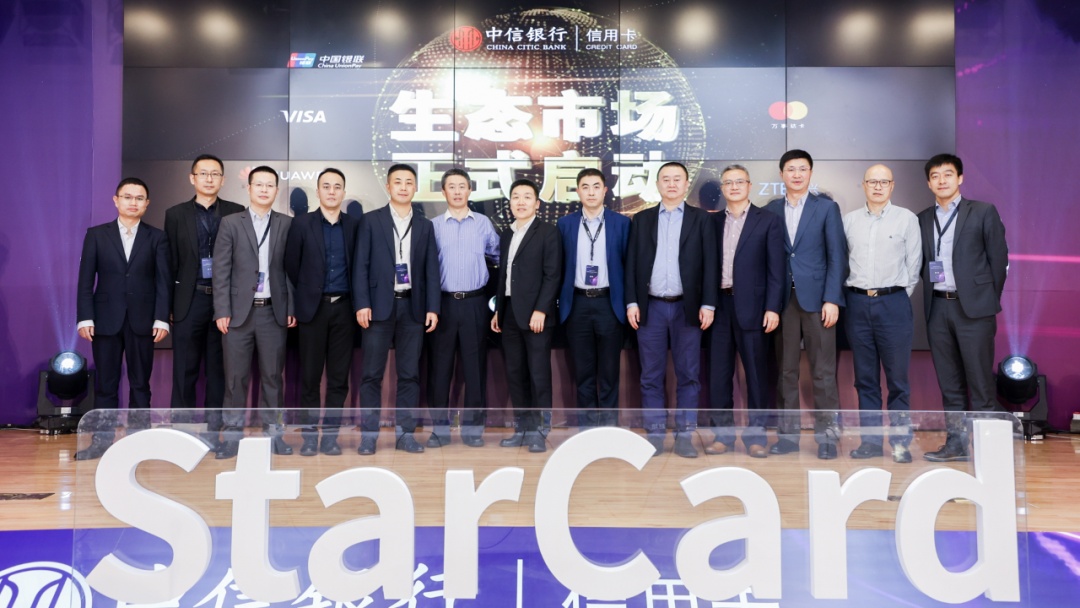
StarCard is not only a new core system, but also helps CITIC Bank to improve its comprehensive ability of "new service, new technology and new management" in credit card business. However, its successful landing has also faced many challenges. Dismantling this case may give reference value to banking innovation, credit card business development, financial technology and many other aspects.
one
The engine of the climbing plane needs to be replaced. How can the banking giant make this process no longer thrilling?
The main background for CITIC Bank to upgrade its credit card core system lies in the leap-forward development of its business, which makes it necessary to upgrade its information system at one time, instead of re-optimizing the old generation.
As early as five or six years ago, CITIC Bank’s credit card system faced the situation that the mainstream credit card supplier system in the world could not meet the requirements of leap-forward development. From the perspective of capacity demand alone, the bank’s credit card business faced a leap from 40 million to 100 million. In addition, the bank system has been pursuing autonomy for these years, so it is imperative to independently create and launch a core system that meets the requirements of the times.
However, the information system is divided into two parts: the core system and the peripheral system. For the banking industry, it is more difficult to replace the core system. When a bank’s business is frequent and growing rapidly, replacing the core system is tantamount to replacing its engine when the plane takes off and climbs, which is very challenging and thrilling.
StarCard finally landed successfully, which shows that CITIC has successfully met the challenge. Looking back, there are three reasons why it can be done.
1. In the overall layout, the implementation strategy of "periphery first, core later" has been formulated and adhered to in the long-term vision.
This is equivalent to a road map to guide the realization process of the whole leap-forward development.
This has brought several benefits:
First, verify the cloud architecture and other new technical forms that the core system needs to use in the non-core system, and first use the peripheral system to "swim" to accumulate experience, find and correct problems;
Second, through the construction of the peripheral system, the technical framework and tool system are established, which is equivalent to making all preparations for the change of the core system and clearing away the unnecessary system and technical obstacles;
Third, the construction of the peripheral system can train the team and cultivate talents, and reserve strength for the replacement of the core system.
Although StarCard has just been put into production for one year, the "peripheral first, core later" behind it has been implemented for several years, and 126 sets of peripheral systems have been delivered.
2. In concrete implementation, the technology and ability of surgery have been promoted in many dimensions, with bold breakthrough and precise guidance.
In terms of resource allocation, CITIC Bank’s credit card has changed the common practice that the traditional bank core system invests 80% of its resources in hardware equipment, and put more resources into software according to the inverted 28 principle, so as to release the pressure of the core system on hardware equipment through large-scale application of open source technology. Typical needs such as big data storage are mainly solved by combining the current concept of "software definition";
In terms of team management and task promotion, CITIC has set up a so-called "combat column" according to business units in project team management to enhance the ability of collaborative project promotion, and at the same time, through the digital management of personnel, it can locate the progress of everyone from the manpower distribution map;
In terms of testing, CITIC Bank’s credit card used a two-line parallel method to carry out large-scale business testing, and finally achieved nearly 500,000 test cases, simulated nearly 600 abnormal scenarios, timely screened out possible problems during official operation and solved them in advance. Before going online, it also conducted non-inductive switching drills in the same city computer room according to regulatory requirements;
In addition, on the technical level, CITIC has also built an AaaS platform (API as a Service) and a OneData real-time big data service platform. After going online, it is also equipped with an intelligent operation and maintenance system that can intelligently alarm and dispatch tasks in real time.
……
All of these make StarCard’s production not only a technological change, but also an upgrade of management, which promotes the whole IT R&D to form a new management model, and thus forms the trinity of "new service, new technology and new management".
3. In terms of external cooperation, a large and orderly collaborative team has been built.
Partner capacity input is an important external supporting force for the launch of CITIC Bank’s credit card StarCard. Starcard belongs to CITIC Bank’s credit card, but it is the result of the joint efforts of all partners, which highlights the standard paradigm needed by a bank’s innovative core system in the digital age, that is, to realize the synergy of interests in the huge and complicated cooperation process and build a business community, not just the business cooperation between Party A and Party B.
StarCard took 23 months to produce and migrate the old system. It has a technical team of more than 1,000 people, delivering four major versions and tens of thousands of function points, which can not be separated from the support of various partners.
Huawei has the ability to provide cloud, 5G, AI and other aspects, which is based on the long-term strategic cooperation between CITIC Bank Credit Card Center and Huawei;
GoldenDB, a financial-grade distributed database jointly developed by ZTE and China CITIC Bank, makes StarCard not only the world’s first core system with all-cloud credit card system and distributed data, but also the first application of distributed database in the financial industry.
The container cloud technology provided by Red Hat software greatly improves the agility of the system;
In addition, there are partners such as Jiang Rongxin, Changliang, Tianyang, KPMG, etc., which support StarCard from research and development to management, and in turn, StarCard has become a high-quality case for them to serve the financial industry.
It can be said that from the "preparation period" in the first few years of StarCard’s production to the practical period of one year after its production, all partners have run into a community of technology and interests.
2
In the face of diversified competition pressure, what does the core system upgrade bring to the bank credit card business?
As a core system with three dimensions of service+technology+management innovation, StarCard, which makes the leap-forward development of credit cards stable, has brought four values to the credit card business of CITIC Bank, and also inspired the whole banking industry to view the value potential of a new core system.
1. Bearing capacity: Show "technical muscle" in the face of skyrocketing business.
The most important ability of a core system is the bearing capacity of the business, just as a person’s strength is first reflected in the muscles.
After a year of stable operation, in the latest data, StarCard has successfully carried 110 million account operation management, and the overall transaction success rate is 99.999%, that is, the high availability rate of "five 9s", while the traditional core system has only reached "four 9s" at the highest.
In addition, StarCard faces a transaction peak of up to 4500 TPS. The greatest value of this ability lies in the core system’s stronger ability to cope with the "tidal phenomenon" that frequently appears in the current consumer economy. It can not only effectively meet the high-frequency trading scenarios such as member days, snapping up and rushing for cash, and marketing activities, but also be able to cope with the peak value in a more economical way without upgrading the hardware equipment.
The test results prove this point. StarCard can support the pressure side value of 20,000 TPS with 20 X86. In contrast, the peak value of double eleven in domestic big banks may be less than 10,000.
2. Reactivity: The business has both strength and "ingenuity"
The ability to dynamically adapt to the environment is the ability that a credit card core system must improve beyond the "muscle" of bearing capacity. Just like a muscular warrior, it is necessary to cultivate flexible response moves, otherwise it is easy to be unable to adapt to the new battlefield situation.
In this regard, the StarCard system was rebuilt based on the era of big data, and it was naturally endowed with such "ingenuity".
Typically, if you can achieve flexible micro-services, you can turn the original complex banking system into a small function of a unit, decouple the system from the service level, parameterize and modularize, and realize more agile development, which is a bit like disassembling the system in blocks and combining the new services and functions you want, which is very flexible and creates unlimited development possibilities.
In addition, CITIC Bank Credit Card also landed the first real-time pre-evaluation system of business strategy of "unitization+gray release" in the industry, which is a system that can effectively reduce the risk of new product release, which is equivalent to conducting a simulation very close to the real situation before the real product is launched, predicting and evaluating the effect and influence of business execution, and feeding back the results to the product side for optimization and adjustment.
All these come from the advantages of the cloud architecture chosen by StarCard compared with the traditional architecture, which can maintain business agility while maintaining large capacity.
3, service power: no fear of competing with Internet products "wrestling"
Although banks have extensive cooperation with Internet platforms, it must be said that in the case of credit cards, banks are under considerable pressure in the face of credit consumption products of Internet platforms-in fact, this is also an important driving force for the reform and upgrading of credit cards.
The arrival of StarCard also shoulders this mission. After enriching muscles and being skillful, it can also break off the wrist with Internet opponents.
In addition to the expansion of more commercial resources of the bank itself, from the perspective of StarCard technology, this qualification of "wrestling" comes from the improvement of user experience in three aspects:
First, the experience of shorter transaction response time. The success rate of "5 9s" and the peak value of 4500TPS did not sacrifice the response time. The service response time of each authorized transaction of StarCard was within 40 milliseconds.
Second, the integration of more cutting-edge interactive capabilities. CITIC Bank Credit Card reconstructs the business process and rewrites the source code, combining new scientific and technological capabilities, such as face recognition, to enhance the user’s consumption experience and achieve parity with Internet products;
The third is to change the lack of basic functions of the traditional core system in terms of balance segmentation and transaction-level pricing, and create more product strategies in terms of payment, balance segmentation and hierarchical pricing, thus enriching the user experience.
Of course, this must also be upgraded in line with the concept of credit card operation.
4. Security: Keep the data "comprehensive" during personal consumption.
The security of consumers’ personal information has attracted more and more attention in the wave of consumer finance development, and even those internet platforms with successful products have been criticized in some aspects.
There are muscles, ingenuity, and wrists. Finally, we must ensure our own "comprehensiveness" in the fierce competition.
In this respect, banks have more advantages. StarCard’s new core system has been systematically arranged at the level of intelligent risk control. By strengthening centralized management and integrating back-end independent authentication modules, it can realize the ability of unified user login and optimized user rights management. On the one hand, it can manage users more effectively, on the other hand, the information security of cardholders is more secure.
In other words, this was originally the ability that banks must have under the banner of compliance, and StarCard only further strengthened it.
three
The credit card "ecology" is advanced, from focusing on the commercial side to multi-terminal integration.
At the first anniversary salon of StarCard’s new core system, CITIC Bank Credit Card also officially launched the "ecological market" of credit card finance technology, and opened a new digital finance format called "unbounded opening". Its practice is to create a variety of formats with partners around N scenarios such as "risk, market, sales and operation" based on the new core system, and realize the "1+N+∞" model.
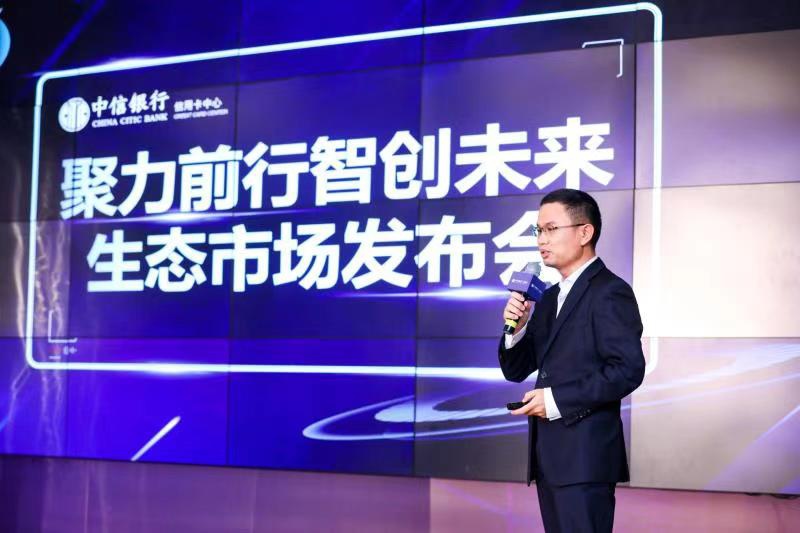
In the past, the most talked about the "ecology" of credit cards was the actual consumer rights that merchants could provide to consumers through cooperation. But in fact, with the increasing business volume and diversified consumer demand, and the external contact of credit card business is no longer limited to C-end users, to better meet the market demand, it is increasingly necessary to support the cooperation of various resources including technology.
What CITIC Bank’s credit card wants to do is to get through and seamlessly integrate from technology to business scenarios, extend the ecology, integrate both the business demand side and the eco-partners at the technology side, and realize a form that can be called an "ecological complex" to gain a longer-term competitive advantage, and always have the motivation for endogenous growth.
It can be seen that the elements of this "ecological complex" are increasingly rich, including card organizations (UnionPay, Visa, MasterCard, etc.), technology companies (Huawei, ZTE, Red Hat, Jiang Rongxin, Changliang, Tianyang Hongye, etc.), consulting companies (KPMG, etc.), credit card service providers and many other types of partners, and export brand promotion, joint operation, customer operation, risk detection, etc.
Obviously, the "unbounded opening" of CITIC Bank’s credit card joint partners has not stopped. Recently, the ARM server pressure test is being carried out, and it is said that the effect is good. According to the idea of CITIC Bank’s credit card, it will "continue to enrich the credit card business ecology, build a" business+technology "platform system, and extend its functions and transactions in all walks of life"-it seems that the first anniversary of StarCard’s production is only the beginning, and the future financial industry will be innovated.
* The pictures in this article are all from the Internet.
* This content is original [Science and Technology Directions]. Without authorization, no one may use it in any way, including reprinting, excerpting, copying or creating mirror images.
[End]
Zeng Xiangling
1 Titanium Media, Pintu, Everyone is a product manager and many other top ten authors of venture capital and technology websites of the year;
2 Tiger Roar Award judges;
3 writers: [Business opportunities under the new normal of mobile internet plus] and other best-selling authors;
4 Special commentators of nearly ten newspapers and magazines such as China Business News (blog, Weibo), Business, Business Review, Sales and Market;
5 Nearly 80 columnists including Titanium Media, 36kr, Tiger Sniff, Interface and The Paper;
The concept of "brain artist" (brain craftsman) has evolved into "self-media" and has become an industry;
7 Tencent all-media sent honorary tutors and communication consultants of many scientific and technological intelligence companies.
Key areas of concern
1 Artificial Intelligence | Blockchain | Automobile Industry Chain | Content Entrepreneurship | New Retail
2 E-commerce | New Media Marketing | Enterprise Service | Home Industry | Community O2O
3 Smartphone | online celebrity | Sports IP | Internet Finance | UAV
4 Sharing economy | Live broadcast, short video | Traditional enterprise transformation
Latest works
This article was first published on WeChat WeChat official account: Science and Technology Directions. The content of the article belongs to the author’s personal opinion and does not represent Hexun.com’s position. Investors should operate accordingly, at their own risk.